RL-16 SLIP: TRUST INCOME
July 12, 2024
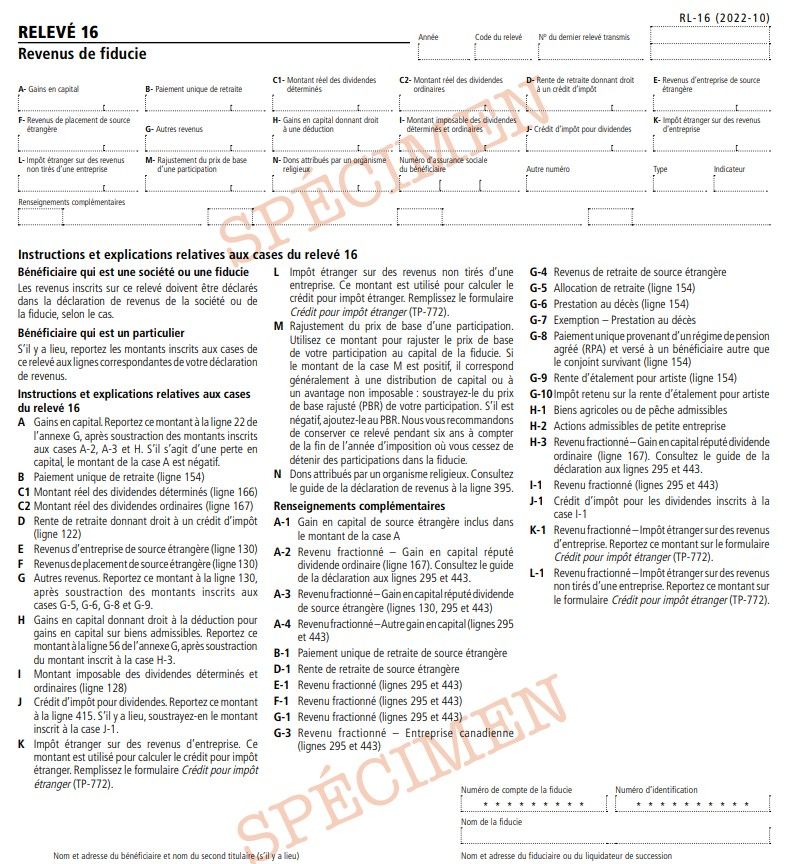
RL-16 SLIP: TRUST INCOME
The RL-16 slip must be filed by trusts to report amounts allocated to their beneficiaries.The information on the RL-16 slip is used by beneficiaries to complete the personal income tax return (TP-1-V), the Déclaration de revenus des sociétés (CO-17) or the Trust Income Tax Return
How to Complete the RL-16 Slip (Box by Box Instructions)
Box A
Capital gains. Subtract the amounts in boxes A-2, A-3 and H from the amount in box A and enter the result on line 22 of Schedule G. In the case of a capital loss, the amount in box A is negative.
Box B
Single pension payment (line 154).
Box C1
Actual amount of eligible dividends (line 166).
Box C2
Actual amount of ordinary dividends (line 167).
Box D
Retirement pension giving entitlement to a tax credit (line 122).
Box E
Foreign business income (line 130).
Box F
Foreign investment income (line 130)
Box G
Other income. Subtract the amounts in boxes G-5, G-6, G-8 and G-9 from the amount in box G and enter the result on line 130 of the return.
Box H
Capital gains eligible for the capital gains deduction on qualified property. Subtract the amount in box H-3 from the amount in box H and enter the result on line 56 of Schedule G.
Box I
Taxable amount of eligible dividends and ordinary dividends (line 128).
Box J
Dividend tax credit. Enter this amount on line 415 of the return, after subtracting, where applicable, any amount indicated in box J-1.
Box K
Foreign income tax on business income. This amount is used to calculate the foreign tax credit. Complete form TP-772-V, Foreign Tax Credit
Box L
Foreign income tax on non-business income. This amount is used to calculate the foreign tax credit. Complete form TP-772-V, Foreign Tax Credit.
Box M
Cost base adjustment of capital interest. Use this amount to adjust the cost base of your capital interest in the trust. If the amount in box M is positive, it generally corresponds to a distribution of capital or a non-taxable benefit. Subtract this amount from the adjusted cost base (ACB) of your capital interest. If the amount is negative, add it to your ACB. We recommend that you keep the RL-16 slip for six years after the end of the taxation year in which you cease to hold interests in the trust.
Box N
Donations allocated by a religious organization. See the instructions for line 395 in the guide to the income tax return.
Boxes under “Renseignements complémentaires” (additional information) Box A-1
Foreign capital gain included in box A
Box A-2
Split income: Capital gain deemed to be an ordinary dividend (line 167). See the instructions for lines 295 and 443 in the guide to the income tax return.
Box A-3
Split income: Capital gain deemed to be a foreign dividend (lines 130, 295 and 443)
Box A-4
Split income – Other capital gain (lines 295 and 443)
Box B-1
Single foreign pension payment
Box D-1
Foreign retirement pension
Box E-1
Split income (lines 295 and 443)
Box F-1
Split income (lines 295 and 443)
Box G-1
Split income (lines 295 and 443)
Box G-3
Split income: Canadian corporation (lines 295 and 443)
Box G-4
Foreign retirement income
Box G-5
Retiring allowance (line 154)
Box G-6
Death benefit (line 154)
Box G-7
Death benefit: Amount of the exemption
Box G-8
Single payment from a registered pension plan (RPP) made to a recipient other than the surviving spouse (line 154)
Box G-9
Income-averaging annuity for artists (line 154)
Box G-10
0 Income tax deducted at source on the income-averaging annuity for artists
Box H-1
Qualified farm or fishing property
Box H-2
Qualified small business corporation shares
Box H-3
Split income: Capital gain deemed to be an ordinary dividend (line 167). See the instructions for lines 295 and 443 in the guide to the income tax return
Box I-1
Split income (lines 295 and 443)
Box J-1
Tax credit for the dividends entered in box I-1
Box K-1
Split income: Foreign income tax on business income. Enter this amount on form TP-772-V, Foreign Tax Credit
Box L-1
Split income: Foreign income tax on non-business income. Enter this amount on form TP-772-V, Foreign Tax Credit
For further information please contact Taxtron Support at 416-491-0333 or visit www.taxtron.ca (opens in a new tab)